Oman’s New Recruitment Regulations 2027: Licensing, Worker Protection, Mandatory Insurance and Employer Refund Rights
Introduction
Oman's Ministry of Labour has issued Ministerial Decision No. 390/2026, promulgating a new Regulation Governing the Practice of Recruiting Non-Omani Manpower. Published in Official Gazette No. 1669 on 11 October 2026, the Decision repeals the previous recruitment framework under Ministerial Decision No. 1/2011 and introduces a revised regime for licensing, recruitment operations, contractual safeguards and the protection of workers and employers.
The regulation represents a significant development for manpower recruitment offices, domestic-worker recruitment agencies, employers and businesses that depend on expatriate labour. It establishes more prescriptive requirements for ownership, licensing, financial security, accommodation, insurance, recruitment timelines and the handling of complaints and refunds.
The new framework takes effect on 1 January 2027. Existing licences remain valid until their respective expiry dates, but subsequent renewals must comply with the new regulation.
1. Licensing and eligibility requirements
Articles 2 and 8 establish that recruitment activity may be carried on only with a licence issued by the Ministry of Labour. The Ministry may also temporarily suspend the grant of new licences where the public interest requires it.
The principal eligibility conditions include:
-
Omani ownership: The establishment's owner, partners and authorised signatories must be Omani nationals.
-
Dedicated management: The owner or at least one partner must devote themselves to the activity and be registered with the Ministry as an employer.
-
SME registration: The establishment must be registered with the Small and Medium Enterprises Development Authority.
-
Minimum age: The owner and each partner must be at least 23 years old.
-
Qualifications or experience: The owner or partner dedicated to management must hold at least a General Education Diploma or have at least five years of practical experience in non-Omani manpower recruitment.
-
Financial security: A financial guarantee of OMR 5,000 must be deposited in the designated Ministry account.
-
Licence fee: The prescribed licensing fee is OMR 300.
The regulation also establishes restrictions concerning existing or previously cancelled recruitment licences and certain criminal convictions. The Ministry may assess the applicant's competence through an interview or a prescribed training programme.
These conditions have important implications for investors considering entry into the recruitment sector. General company incorporation or foreign-investment eligibility should not be treated as sufficient authority to undertake a specifically regulated recruitment activity.
2. Premises, accommodation and license renewal
Article 10 requires recruitment offices to maintain premises measuring at least 80 square metres, including adequate space for workers to rest. Suitable accommodation must be provided separately for male and female workers, with the applicable occupational health and safety requirements observed.
Under Articles 12 and 13, the licence is issued following satisfaction of the prescribed requirements, including the provision of premises and worker accommodation within the stipulated period. The licence remains valid for two years and may be renewed for further two-year periods.
Renewal applications must be submitted at least 30 days before expiry.
Article 16 permits an application for a branch after the recruitment office has held its licence for at least one year. The branch must satisfy the prescribed conditions, including a separate OMR 5,000 financial guarantee, a fee of OMR 300 and the appointment of an Omani branch manager. Additional accommodation requirements apply where the branch is more than 50 kilometres from the nearest accommodation maintained by the office.
Changes to approved premises or worker accommodation require prior written approval. Transfers of licences and changes in partners are also subject to the competent authority's approval.
3. Temporary recruitment of domestic workers
Articles 19–22 introduce a structured temporary work-permit mechanism for non-Omani workers in domestic-worker occupations and equivalent categories, pending transfer of their services to an employer.
Each temporary permit is valid for 180 days, cannot be renewed and is subject to a maximum of 25 permits per branch. The prescribed fee is OMR 26 per permit.
Recruitment offices must provide a monthly allowance while the worker remains with the office awaiting transfer:
-
Days 1–60: 60% of the monthly wage stated in the job offer.
-
Days 61–180: 100% of the monthly wage stated in the job offer.
The office must also provide accommodation, food and necessary healthcare without charge.
Trial periods and transfer of services
Article 22 permits a seven-day trial period before the worker's services are formally transferred to an employer. This enables the employer to assess professional suitability and conduct while allowing the worker to assess the working environment.
The combined trial periods for an individual worker cannot exceed 28 days during the temporary stay, and the worker cannot be placed on trial with more than four employers. A worker may not be trialled more than once by the same employer.
At the end of the trial, the employer must complete the transfer formalities or bear the applicable departure costs if the employment is not proceeding.
These provisions require recruitment offices to manage temporary placements carefully, particularly the associated wage allowances, accommodation, healthcare and repatriation obligations.
4. Mandatory contracts and pre-arrival disclosures
Article 5 requires recruitment offices to use the prescribed forms for job offers and contracts relating to recruitment or transfer of services. Contractual terms inconsistent with the prescribed forms are void unless they are more favourable to the employer.
Article 27 requires workers to receive written information before arriving in Oman concerning the nature of their duties, employment conditions and agreed remuneration. The job offer must be signed by the employer, and the worker's prior agreement must be obtained before the recruitment office concludes the service contract and secures the competent authority's approval.
This framework is intended to reduce discrepancies between the occupation or remuneration offered during recruitment and the conditions ultimately encountered at the workplace.
Employers should ensure that their recruitment instructions, written offers and employment documentation accurately reflect the actual position being offered.
5. Recruitment deadlines and compensation for delay
Articles 29 and 30 establish a maximum recruitment period of 45 days from the conclusion of the service contract, unless the parties agree to a shorter period.
Where the recruitment office fails to meet the applicable deadline, the employer may terminate the contract or grant an additional period of up to 30 days by written agreement.
Subject to the regulation's conditions, the employer may claim compensation equivalent to 5% of the service fee. Amounts due must be refunded within 15 days of termination.
An exception applies where the delay results from force majeure or an emergency, provided the recruitment office gives written notice supported by documentary evidence within three days of the event. If the impediment continues for more than 30 days without recruitment, the service fee must be refunded. A refund is also required where the worker dies before arriving in Oman.
These provisions give employers a clearer contractual mechanism for addressing delays and recovering payments.
6. Mandatory insurance for recruitment contracts
Article 28 requires recruitment offices to maintain insurance coverage for each service contract. The prescribed coverage includes compensation to the employer for all or part of the service fee, where applicable under Article 32, and the worker's return-ticket costs.
The regulation specifies different commencement rules for certain categories of insurance coverage. Accordingly, the policy wording, applicable exclusions and relevant statutory provisions must be reviewed together rather than assuming that every risk is covered from the same date.
A copy of the insurance policy must be provided to the employer when the service contract is concluded.
Recruitment offices should review their insurance arrangements before the regulation takes effect. Employers, in turn, should obtain and retain the policy documentation and verify that the relevant contractual risks fall within its coverage.
7. Refunds and the service-guarantee regime
Article 32 identifies circumstances in which a recruitment office must refund the service fee, or the relevant portion, within 15 days of the worker's return to the office, unless the parties agree in writing to a replacement.
The specified circumstances include:
-
A material discrepancy between the worker's actual occupation and the occupation or requirements agreed in the offer, subject to the applicable trial-period conditions.
-
Refusal to work without an acceptable excuse or departure from employment without a lawful reason.
-
Certain established medical or physical unfitness conditions.
-
Specified assault or criminal conduct supported by the required evidence.
-
Return requested by the overseas recruitment agency for a reason not attributable to the employer.
-
Natural death during employment while the employment contract remains valid.
-
Qualifying total or partial disability arising from a health condition occurring after arrival in Oman.
The applicable refund entitlement depends on the particular circumstances and the statutory conditions.
Employer notification obligations
Under Article 33, the employer must notify the recruitment office within 30 days of the relevant event. Failure to comply may permit a deduction of up to 5% of the service fee.
Employers should therefore establish an internal process for documenting complaints, medical findings, abandonment of work, return requests and other events that may trigger a refund.
Circumstances excluding refund rights
Article 34 excludes the employer's right to recover the service fee in specified circumstances, including deception by the employer concerning working conditions, non-payment of wages for more than two consecutive months or three non-consecutive months within a year, certain forms of harassment or violence, and knowingly failing to address a serious threat to the worker's safety or health.
The refund mechanism is therefore not an unconditional guarantee. Both parties must comply with their respective legal obligations.
8. Operational obligations of recruitment offices
Article 23 imposes continuing obligations beyond the initial licensing process. Recruitment offices must, among other things:
-
Display their licence prominently at the approved premises.
-
Restrict their operations to the licensed activity.
-
Maintain direct management and supervision by the owner or dedicated partner.
-
Notify the Ministry of agreements with overseas recruitment agencies and provide certified Arabic translations.
-
Retain receipts for payments to overseas agencies for five years.
-
Maintain receipts for amounts collected from employers until the relevant employment contract ends.
-
Provide employers with available information concerning workers' skills and experience.
-
Arrange required pre-arrival medical examinations.
-
Inform workers about their rights, obligations, local customs and available complaint channels.
-
Refrain from retaining workers' passports or official documents without their written consent.
-
Refrain from charging workers recruitment or employment fees.
-
Avoid placing returned workers with another employer before the required transfer formalities are completed.
Article 24 also requires an updated electronic register recording worker details, occupations, wages, nationalities, employers, overseas recruitment agencies and information concerning workers returned to the office.
These obligations require appropriate recordkeeping, staff training and documented internal procedures.
9. Penalties and enforcement
The regulation provides for administrative fines and, in specified circumstances, suspension or cancellation of a recruitment licence.
Examples of prescribed penalties include:
| Violation | Prescribed consequence |
|---|---|
| Changing approved premises or accommodation without prior approval | OMR 500 |
| Transferring a licence without approval | OMR 500 and licence cancellation |
| Allowing a non-Omani to manage the recruitment office | OMR 500 and removal of the offending manager at the office's expense |
| Conducting another business from the licensed premises | OMR 300 |
| Failure to insure a service contract | OMR 200 per uninsured contract, together with applicable refund consequences |
| Failure to pay the prescribed temporary-worker allowance | OMR 100 per affected worker |
| Failure to carry out the required medical examination | OMR 200 per affected worker |
| Recruitment through unapproved overseas agencies | OMR 500 per worker |
These examples are not exhaustive. Other violations carry their own penalties, and repeated breaches may attract increased fines or more serious licensing consequences.
Recruitment offices should review the complete schedule of violations rather than treating the above examples as a comprehensive statement of potential liability.
10. Transitional considerations and recommended action
The Decision takes effect on 1 January 2027. Existing licences remain valid until expiry, but renewals must satisfy the new framework.
Recruitment offices should use the period before commencement to undertake a structured compliance review. Priority actions include:
-
Verifying ownership, management eligibility and SME registration.
-
Reviewing premises, worker accommodation and branch arrangements.
-
Updating service contracts and job-offer forms.
-
Arranging the required insurance for each service contract.
-
Establishing procedures for recruitment deadlines, refunds and employer notifications.
-
Auditing overseas recruitment agency approvals and related documentation.
-
Updating electronic records, receipts and document-retention procedures.
-
Training staff on worker protection, complaints, temporary permits and repatriation obligations.
Employers should also review recruitment agreements, confirm that agreed occupations and wages are documented accurately, obtain copies of insurance policies and establish procedures for reporting events that may trigger a refund.
Conclusion
Ministerial Decision No. 390/2026 introduces a more detailed regulatory framework for recruiting non-Omani manpower in Oman. Its principal effects concern the eligibility of recruitment-office operators, financial security, accommodation, temporary recruitment, mandatory insurance, contractual transparency and defined refund mechanisms.
For recruitment offices, compliance requires more than obtaining or renewing a licence: it requires appropriate operational systems, records, insurance and worker-management procedures. For employers, the new provisions offer more clearly defined contractual protections while making timely notification and accurate documentation particularly important.
Businesses should assess their existing arrangements against the regulation before 1 January 2027 and seek advice where licensing eligibility, contractual exposure or the application of a particular refund provision is uncertain.
Legal source: Ministerial Decision No. 390/2026, promulgating the Regulation Governing the Practice of Recruiting Non-Omani Manpower, published in Official Gazette No. 1669 on 11 October 2026.
This article is for general legal information and should not be treated as a substitute for advice on the facts of a particular matter.
Oman’s New Tourism Regulations 2026: Key Licensing, Compliance & Operational Changes
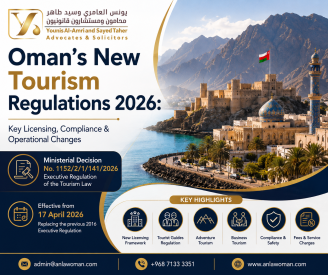
Ministerial Decision No. 1152/2/1/141/2026 – Executive Regulation of the Tourism Law
Oman has introduced a comprehensive new regulatory framework for the tourism sector through Ministerial Decision No. 1152/2/1/141/2026, issued by the Ministry of Heritage and Tourism.
The new Executive Regulation of the Tourism Law came into force on 17 April 2026 and replaces the previous Executive Regulation issued under Ministerial Decision No. 39/2016.
The reform is significant for hotels, travel agencies, tour operators, tourism investors, adventure tourism businesses, tourist guides, and companies operating in the business events sector.
1. A Comprehensive New Tourism Regulatory Framework
The new regulation restructures the licensing and compliance framework for tourism activities in Oman.
Among the principal regulated categories are:
- Tourist and hotel establishments;
- Travel and tourism offices;
- Tourist guides;
- Adventure tourism activities;
- High-art performance groups operating in hotels and restaurants; and
- Business tourism activities, including conferences, exhibitions and corporate incentive programmes.
The express recognition of adventure tourism and business tourism as regulated activities is particularly relevant as Oman continues to develop its tourism and events sectors.
2. Significant Change to Tourism Licensing
One of the most commercially important changes concerns the treatment of tourism licence applications.
Under the new framework, the Ministry generally has 60 days to determine an application. If the Ministry does not issue a decision within the prescribed period, the application may be deemed accepted, subject to satisfaction of the applicable regulatory requirements.
This represents an important change from the previous position and may provide greater certainty to tourism investors and operators.
For investors, licensing certainty can directly affect:
- project commencement;
- financing arrangements;
- lease commitments;
- construction schedules; and
- commercial opening dates.
3. Existing Tourism Establishments Should Review Compliance
The replacement of the previous regulatory framework means that existing tourism establishments should assess whether their current operations remain compliant with the new requirements.
Businesses should consider undertaking a regulatory review covering:
- existing tourism licences;
- permitted activities;
- establishment classification;
- premises and facilities;
- staffing arrangements;
- insurance;
- health, safety and security requirements;
- applicable tourism fees;
- service-charge arrangements; and
- advertising and operational practices.
The Ministry has also called on existing licensed hotel and tourism establishments to regularise their status under the new framework.
4. Adventure Tourism Is Now Specifically Regulated
The regulation introduces a dedicated licensing framework for adventure tourism.
This is particularly relevant to businesses involved in activities such as:
- off-road and desert tourism;
- mountain activities;
- trekking;
- canyoning;
- caving;
- ziplining; and
- other adventure activities.
Adventure-tourism operators face specific safety and risk-management obligations. These include appropriate licensing, security and safety requirements, insurance issued in Oman, specialist licensed guides, risk-management measures and safety plans.
Operators are also expected to consider weather conditions and suspend activities where conditions create safety concerns.
Practical implication
Adventure-tourism businesses should treat safety compliance as an ongoing operational obligation rather than merely a licensing requirement.
5. New Regulatory Framework for Tourist Guides
The regulation provides a more structured framework for tourist guides, including different categories such as:
- general tourist guides;
- location-specific guides; and
- specialised guides.
The framework also regulates matters such as group sizes, permitted activities and professional conduct.
Of particular importance to tourism operators employing expatriates, English-language tourist guiding remains subject to Omani nationality requirements.
Businesses should therefore review their guide recruitment and contracting arrangements.
6. Business Tourism Receives Formal Recognition
Another important development is the recognition of business tourism as a regulated tourism activity.
This encompasses activities connected with:
- conferences;
- exhibitions;
- corporate events; and
- incentive programmes.
The development is particularly relevant to Oman's growing MICE — Meetings, Incentives, Conferences and Exhibitions — sector.
Companies operating in this space should assess whether their activities require licensing or additional approvals under the new framework.
7. Tourism Fees and Service Charges
The regulation also addresses the financial obligations associated with tourism establishments.
According to published commentary on the new regulation, establishments continue to collect a 4% tourism fee for the Ministry and an 8% service charge. The new framework also provides for the service charge to be distributed to employees in cash.
Hotels and tourism establishments should therefore review:
- payroll procedures;
- accounting systems;
- customer invoices;
- employee policies; and
- service-charge distribution mechanisms.
This creates an important intersection between tourism regulation, employment compliance and financial controls.
8. Revised Licence Fees
The new regulation also revises various tourism-related fees.
For example, the reported licence fee for a five-star hotel is OMR 1,900 for three years, compared with the previous fee of OMR 3,200 for five years.
Investors and operators should therefore verify the applicable fee before submitting new applications or renewal requests.
9. Administrative Penalties
The regulation establishes an administrative penalty framework for violations, with administrative fines reported to be capped at OMR 6,000.
The financial exposure reinforces the importance of implementing internal compliance procedures and maintaining appropriate documentation.
10. What Should Tourism Businesses Do Now?
Tourism and hospitality businesses should consider taking the following steps:
Conduct a regulatory gap analysis
Compare existing licences, activities and operational practices against the new regulation.
Review licensing requirements
Confirm whether existing activities fall within a newly regulated category or require additional approvals.
Review employment arrangements
Particularly assess arrangements involving tourist guides, service charges and operational personnel.
Review safety and insurance
Adventure-tourism operators should give particular attention to risk assessments, insurance and emergency procedures.
Review contracts
Hotel management agreements, tourism operator agreements, supplier contracts and customer terms should be reviewed where the regulatory changes affect contractual obligations.
Update internal compliance procedures
Businesses should ensure that staff responsible for licensing, HR, finance and operations understand the new requirements.
Conclusion
Ministerial Decision No. 1152/2/1/141/2026 represents a significant restructuring of Oman's tourism regulatory framework.
The regulation goes beyond licensing and introduces more detailed requirements concerning tourism activities, adventure tourism, tourist guides, business tourism, safety, fees and administrative compliance.
For existing operators, the priority should be a regulatory gap assessment and status review. For new investors, the regulatory framework should be considered at the project-planning stage, before committing to significant leases, financing, construction or operational expenditure.
The new framework also presents opportunities for investors by providing greater regulatory clarity for emerging areas such as adventure and business tourism.
YLAW – Legal Perspective
Businesses operating in Oman's tourism and hospitality sector should approach the new regulation as an ongoing compliance framework rather than a one-time licensing requirement.
A structured legal review can help identify licensing gaps, operational risks, contractual issues and potential regulatory exposure before they develop into disputes or enforcement matters.
Younis Al Amri & Sayed Taher Advocates & Solicitors (YLAW) advises businesses and investors on regulatory compliance, corporate structuring, commercial contracts, employment matters, licensing and investment-related legal issues in Oman.
This article is intended for general information only and does not constitute legal advice. Businesses should obtain advice based on their specific activities, licences and regulatory circumstances.
Oman E-Invoicing: Key Changes Under Tax Authority Decision No. 189/2026
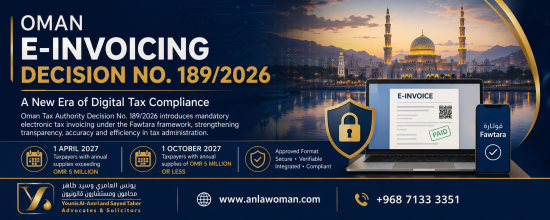
Oman has taken another significant step towards digital tax administration with the introduction of Tax Authority Decision No. 189/2026, establishing the framework for mandatory electronic tax invoicing in the Sultanate.
The reform forms part of Oman's Fawtara electronic invoicing initiative and will progressively move VAT-registered businesses from conventional invoicing to a secure, structured electronic invoicing environment.
For businesses, the change is not simply about replacing paper invoices with electronic documents. It will affect VAT compliance, accounting systems, ERP platforms, invoice controls, data management, record retention and internal processes.
With mandatory implementation scheduled in 2027, businesses should begin preparing now.
1. What Is Oman Tax Authority Decision No. 189/2026?
Tax Authority Decision No. 189/2026 introduces amendments to the VAT regulatory framework relating to the issuance of tax invoices in electronic form.
The Decision provides the legal foundation for the transition towards mandatory electronic tax invoicing, complementing the Oman Tax Authority's Fawtara project.
The objective is to establish a more standardised and secure process for the generation, exchange, verification and storage of tax invoices.
The wider Fawtara initiative is intended to strengthen tax compliance, improve transaction transparency and facilitate more efficient tax administration.
2. What Is E-Invoicing in Oman?
Electronic invoicing, commonly referred to as e-invoicing, involves the creation, exchange and storage of tax invoices in a prescribed electronic format.
An important distinction should be made between an electronic invoice and an ordinary electronic document.
A PDF invoice sent by email, for example, is still essentially a digital representation of a conventional invoice. It does not necessarily satisfy the requirements of a structured electronic invoicing system.
Under Oman's Fawtara framework, electronic invoices are intended to be generated and exchanged in a standardised format capable of automated processing and verification.
3. Key Requirements for Electronic Tax Invoices
The new framework places greater emphasis on the security and integrity of tax-invoice information.
Businesses will need to ensure that their electronic tax invoices satisfy the applicable requirements concerning:
- Approved electronic format – invoices must be generated using the electronic format and technical specifications prescribed by the Tax Authority.
- Security – the invoicing process must protect invoice information against unauthorised alteration or manipulation.
- Integrity – the information contained in the invoice must remain reliable and complete.
- Unique identification – each invoice must be capable of being uniquely identified within the electronic invoicing framework.
- Electronic storage – invoices must be retained electronically in accordance with the applicable requirements.
- Verifiability – the system should allow invoices to be authenticated and verified through the prescribed electronic mechanism.
These requirements mean that businesses should assess the entire invoicing process rather than simply redesigning their invoice template.
4. Is a PDF Invoice an E-Invoice?
Not necessarily.
One of the most important practical points for businesses is that a conventional PDF invoice should not be assumed to constitute a compliant electronic tax invoice.
The Fawtara model is based on structured electronic data that can be processed and exchanged through the approved electronic infrastructure.
Accordingly, once mandatory e-invoicing applies to a taxpayer, simply generating a PDF from accounting software and emailing it to a customer may not satisfy the applicable requirements.
Businesses should therefore review whether their current accounting and ERP systems are capable of supporting the required e-invoicing functionality.
5. Who Will Be Required to Comply?
The electronic invoicing framework is being introduced progressively for businesses falling within the relevant VAT regime.
The OMR 5 million annual-supply threshold is particularly important because it determines the applicable mandatory implementation date.
Businesses should therefore establish their annual supply value and determine which implementation category applies to them.
The reform should not be viewed as affecting only large corporations. Businesses below the OMR 5 million threshold will also need to prepare for the subsequent implementation stage.
6. Mandatory E-Invoicing Deadlines
The mandatory implementation is divided into two principal stages:
| Taxpayer category | Mandatory implementation |
|---|---|
| Annual supplies exceeding OMR 5 million | 1 April 2027 |
| Annual supplies OMR 5 million or less | 1 October 2027 |
The first group therefore has the earlier compliance deadline.
Businesses should begin their implementation programme well before these dates because ERP integration, service-provider selection, testing, data cleansing and employee training may require considerable preparation.
7. What Is Fawtara?
Fawtara is the Oman Tax Authority's electronic invoicing initiative designed to establish a digital ecosystem for tax invoices.
The system is intended to facilitate the electronic creation, exchange, validation and reporting of invoice information.
The Fawtara framework connects the relevant parties in the invoicing chain and enables the Tax Authority to receive relevant tax information electronically.
The initiative forms part of Oman's wider digital transformation of tax administration.
8. Role of E-Invoicing Service Providers
Accredited e-invoicing service providers will play an important role in the Fawtara ecosystem.
Businesses may need to connect their accounting or ERP systems with an approved service provider capable of processing and exchanging electronic invoices in accordance with the Tax Authority's requirements.
When selecting a service provider, businesses should consider:
- technical compatibility;
- integration capabilities;
- information security;
- data protection;
- system availability;
- implementation support;
- scalability; and
- contractual liability for system failures.
The choice of service provider should therefore be treated as a legal, technological and commercial decision, rather than simply a software procurement exercise.
9. The Five-Corner Model
Oman's Fawtara framework is designed around a five-corner model involving:
- Supplier – the business issuing the invoice.
- Supplier's service provider – the accredited provider processing the invoice.
- Buyer – the customer receiving the invoice.
- Buyer's service provider – the provider processing the invoice for the recipient.
- Oman Tax Authority – the regulatory authority receiving relevant tax information.
This model is intended to facilitate secure electronic exchange and improve the accuracy and efficiency of invoice reporting.
10. Impact on VAT Compliance
E-invoicing does not replace the underlying VAT obligations of a taxpayer.
Businesses will continue to be responsible for correctly determining matters such as:
- whether a supply is taxable;
- the applicable VAT rate;
- the taxable value;
- the time of supply;
- VAT identification details;
- credit and debit notes; and
- VAT return reporting.
The difference is that these tax obligations will increasingly be supported by an automated electronic invoicing environment.
Errors that may previously have remained within a paper-based process could therefore become more visible through electronic validation and reporting.
11. Impact on Accounting and ERP Systems
The introduction of mandatory e-invoicing will require many businesses to reassess their existing accounting infrastructure.
Businesses should determine whether their current systems can:
- generate compliant electronic invoices;
- capture all mandatory invoice information;
- communicate with the relevant service provider;
- receive electronic invoices;
- process credit and debit notes;
- maintain appropriate audit trails;
- securely store invoice data; and
- retrieve records when required.
Where existing systems are not compatible, businesses may need to upgrade their ERP or accounting platform or introduce an appropriate integration solution.
12. Data Accuracy Will Become More Important
Electronic invoicing increases the importance of accurate master data.
Businesses should review information relating to:
- customer names;
- commercial registration details;
- VAT registration numbers;
- supplier information;
- product and service classifications;
- tax treatment; and
- invoice values.
In an automated environment, inaccurate or incomplete information can result in validation failures, incorrect VAT reporting or delays in processing.
Data cleansing should therefore form part of every business's e-invoicing implementation plan.
13. Electronic Storage and Record Retention
The new framework also reinforces the importance of electronic invoice storage.
Businesses should ensure that their systems provide appropriate:
- electronic archiving;
- access controls;
- backup procedures;
- data security;
- audit trails; and
- retrieval mechanisms.
The ability to produce an invoice and its underlying electronic record during a tax inspection or audit will become increasingly important.
Businesses should also consider how electronic invoice records interact with their broader document-retention and information-security policies.
14. Implications for B2B Transactions
The impact is likely to be particularly significant for business-to-business transactions.
Electronic exchange can reduce manual invoice processing and improve the matching of invoices with purchase orders, goods receipts and payments.
Potential benefits include:
- faster invoice processing;
- improved VAT reconciliation;
- reduced manual errors;
- better accounts-receivable management;
- better accounts-payable controls; and
- improved auditability.
However, these benefits depend on the accuracy and reliability of the underlying systems and data.
15. What About B2C Transactions?
The operational treatment of business-to-consumer transactions may differ from B2B transactions depending on the applicable technical requirements and further Tax Authority guidance.
Businesses operating significant B2C activities should therefore monitor the Tax Authority's technical specifications and implementation guidance closely.
They should not assume that a process designed for B2B invoicing will automatically satisfy the requirements applicable to consumer transactions.
16. What Businesses Should Do Now
Businesses should begin preparing for e-invoicing well before their applicable deadline.
1. Determine the Applicable Deadline
Calculate the business's annual supply value and determine whether it falls above or below the OMR 5 million threshold.
2. Conduct a Compliance Gap Analysis
Compare existing invoicing processes with the new electronic invoicing requirements.
3. Assess ERP and Accounting Systems
Determine whether existing software can support the required electronic invoice format and integration.
4. Select an Appropriate Service Provider
Evaluate accredited providers based on technology, security, integration, support and contractual terms.
5. Cleanse Business Data
Review customer, supplier, VAT and transaction data for accuracy.
6. Test the System
Testing should cover the complete invoice lifecycle, including issuance, validation, transmission, receipt, correction, cancellation and storage.
7. Review Internal Controls
Establish clear responsibility for invoice creation, approval, correction and cancellation.
8. Train Relevant Personnel
Finance, accounting, tax, IT, sales and procurement teams should understand how the new system affects their functions.
17. Legal and Commercial Implications
The significance of electronic invoicing extends beyond tax administration.
Electronic invoices may become important evidence in:
- payment disputes;
- commercial litigation;
- tax audits;
- contractual claims;
- accounting investigations; and
- regulatory proceedings.
Businesses should therefore ensure that their electronic records are maintained in a manner that supports both tax compliance and evidentiary reliability.
Contracts with ERP providers, service providers and outsourced accounting companies should also be reviewed to determine whether responsibility for data security, system availability, errors and regulatory compliance is appropriately allocated.
18. Key Dates at a Glance
| Date | Significance |
| 9 August 2026 | Decision No. 189/2026 issued |
| August 2026 | Initial Fawtara pilot/readiness activity |
| 1 April 2027 | Mandatory e-invoicing for taxpayers exceeding OMR 5 million annual supplies |
| 1 October 2027 | Mandatory e-invoicing for taxpayers at or below OMR 5 million annual supplies |
Businesses should monitor subsequent Tax Authority guidance for technical specifications, onboarding procedures and any further implementation instructions.
19. YLAW Perspective
Decision No. 189/2026 represents a significant development in Oman's tax-compliance landscape.
The transition to mandatory electronic invoicing will require businesses to coordinate tax, finance, accounting, IT, legal and compliance functions.
The most effective approach is to treat e-invoicing as a structured implementation project rather than a last-minute software upgrade.
Businesses should begin with:
Legal assessment → Tax gap analysis → System assessment → Service-provider selection → Data cleansing → Integration → Testing → Staff training → Go-live
Early preparation will help businesses minimise operational disruption and reduce the risk of non-compliance when the applicable mandatory deadline arrives.
Conclusion
Oman's transition to mandatory electronic tax invoicing marks an important stage in the digitalisation of the country's tax administration.
Tax Authority Decision No. 189/2026 provides the legal framework for the transition, while the Fawtara system provides the technological infrastructure through which electronic invoices will be processed.
For businesses, the immediate priority should be to understand their applicable deadline, assess their existing systems and begin preparing for integration.
With mandatory implementation beginning on 1 April 2027 for taxpayers exceeding the OMR 5 million annual-supply threshold and 1 October 2027 for taxpayers at or below that threshold, businesses should begin their readiness programmes without delay.
E-invoicing is not merely a change in invoice format. It is a fundamental change in the way businesses create, exchange, store and manage tax information in Oman.
Disclaimer: This article is intended for general information purposes only and does not constitute legal or tax advice. Businesses should review Decision No. 189/2026, the VAT Law and Executive Regulations, and the latest technical guidance issued by the Oman Tax Authority in determining their specific compliance obligations.
Oman Labour Ministry Urges Employers to Comply with End-of-Service Benefit Rules
The Ministry of Labour’s continued emphasis on employers’ compliance with statutory employment entitlements highlights the importance of properly calculating and settling end-of-service benefits (EOSB) when an employment relationship comes to an end.
For employers operating in Oman, end-of-service gratuity remains an important statutory obligation, particularly during the transition towards the Savings/Provident Scheme under the Social Protection Law.
1. What does the Labour Law provide?
Under Article 61 of Royal Decree No. 53/2023 issuing the Labour Law, an employer must, upon termination of the employment relationship, pay an end-of-service benefit to a worker who is not covered by the Social Protection Law, at a rate of not less than one basic wage for each completed year of service.
Any fraction of a year is calculated proportionately. The employee’s last basic wage is used as the basis for calculating the benefit. Importantly, service that commenced before the current Labour Law came into force is also included when determining the employee’s qualifying period.
In practical terms:
EOSB = Last Basic Wage × Years of Qualifying Service
The calculation is based on the basic wage, rather than the employee’s total or gross remuneration.
2. Who is currently entitled?
The statutory gratuity under Article 61 applies to workers who are not beneficiaries of the Social Protection Law.
Employers should therefore assess each employee individually, taking into account:
- Nationality and applicable social protection coverage;
- Date of commencement of employment;
- Total qualifying service;
- Last basic wage;
- Applicable employment contract and company policies; and
- Whether the employee falls within the transitional arrangements for the Social Protection Fund’s Savings Scheme.
The Social Protection Fund has confirmed that the new savings system is intended to cover end-of-service benefits for non-Omani workers, replacing the employer-paid gratuity for the period covered by the scheme.
3. The transition to the Savings/Provident Scheme
The Social Protection Law introduced a defined-contribution Savings System for non-Omani workers.
Under Articles 135–138 of the Social Protection Law, the scheme is intended to replace employer-paid end-of-service gratuity for non-Omani workers for the period following commencement of the relevant contribution provisions.
However, service accrued before the commencement of the savings contributions remains subject to separate treatment. The employer must settle the earlier gratuity entitlement in accordance with the applicable Labour Law provisions, or may settle it through the Savings System or directly with the worker in accordance with the statutory framework.
The implementation is being phased. Current Social Protection Fund material identifies the mandatory provident arrangement for non-Omani workers as part of the phased rollout, while the latest ILO/Social Protection Fund summary places its implementation within the fourth year of the Social Protection Law's rollout.
Accordingly, employers should not assume that the future provident mechanism eliminates their present obligations in respect of accrued gratuity.
4. Employer-funded savings or supplementary schemes
Employers may have internal gratuity, savings or supplementary benefit arrangements.
Article 48 of the Labour Law recognizes certain employer savings programmes where the programme is approved in accordance with the applicable requirements and the employer's contribution is intended to discharge its statutory gratuity obligation.
Where the programme does not provide an amount equivalent to the employee's statutory entitlement, the employer may remain liable for the difference. Where the employee has personally contributed to such a programme, additional rights may arise under the applicable arrangement.
Employers should therefore review existing benefit schemes rather than assuming that an internal provision automatically satisfies the statutory obligation.
5. What happens when employment ends?
A proper final settlement should identify and calculate all outstanding employee entitlements, including, where applicable:
- End-of-service gratuity;
- Outstanding salary;
- Accrued leave entitlements;
- Contractual benefits and allowances;
- Any other statutory or contractual amounts due.
Employers should also maintain accurate employment records. The Labour Law requires employers to maintain employee files containing, among other matters, the employee’s commencement date, remuneration, leave records and termination details.
The Government’s current digital services also provide mechanisms for recording termination of service and accessing employment records and end-of-service documentation.
6. Key compliance risks for employers
Failure to properly calculate or settle end-of-service entitlements can result in:
- Employee complaints and labour disputes;
- Claims for unpaid statutory benefits;
- Additional financial exposure arising from incorrect calculations;
- Increased scrutiny during employment-related proceedings; and
- Reputational and employee-relations risks.
Employers should particularly avoid relying on outdated gratuity formulas or calculating benefits solely by reference to gross salary.
7. What should employers do now?
Employers in Oman should consider undertaking an EOSB compliance review covering their workforce.
Recommended actions:
1. Audit employee records
Verify joining dates, basic wages, contracts and periods of service.
2. Recalculate accrued gratuity
Identify potential EOSB liabilities using the applicable statutory methodology.
3. Separate historical and future liabilities
For non-Omani employees, distinguish gratuity accrued before the applicable Savings Scheme contribution period from benefits arising under the new system.
4. Review employment contracts and policies
Ensure contractual provisions do not inadvertently understate statutory entitlements.
5. Review internal savings schemes
Confirm whether any employer-funded scheme has the necessary approvals and provides benefits sufficient to satisfy statutory requirements.
6. Prepare for the Social Protection Fund transition
HR, finance and legal teams should monitor implementation requirements and ensure payroll and employee-record systems can accommodate the new framework.
Conclusion
Oman’s evolving employment and social protection framework requires employers to take a proactive rather than reactive approach to end-of-service obligations.
While the Social Protection Fund’s Savings/Provident Scheme represents a significant shift in the way end-of-service benefits for non-Omani workers will be funded, existing accrued rights and current Labour Law obligations remain important during the transition.
For employers, now is an appropriate time to audit gratuity liabilities, review employment documentation and prepare for the next stage of the Social Protection Law’s implementation.
YLAW Perspective:
A structured end-of-service audit can help employers identify historic liabilities, correct calculation practices and align HR and payroll systems with Oman’s evolving labour and social protection framework before disputes arise.
This article is intended for general information only and does not constitute legal advice. Specific employee entitlements should be assessed based on the applicable law, employment contract, employee status and relevant Social Protection Fund provisions.
Oman's New Trade Union Regulations (Ministerial Decision No. 284/2026): Employer Compliance Guide
Introduction
On 9 July 2026, the Ministry of Labour issued Ministerial Decision No. 284/2026, introducing a new regulatory framework governing labour unions in the Sultanate of Oman. The Decision repeals Ministerial Decision No. 500/2018 and establishes updated rules for the formation, governance, administration, and operation of labour unions, sectoral unions, and the General Federation of Oman Workers.
The reforms reflect Oman's continued efforts to strengthen labour relations, promote transparency, and align workplace practices with international labour standards while ensuring a balanced relationship between employers and employees.
For employers, the Decision introduces important compliance obligations that should be incorporated into existing HR policies and employment practices.
Key Objectives of the New Regulation
The new regulations are intended to modernise Oman's labour relations framework and provide greater clarity for both employers and employees. The principal objectives include:
Strengthening Employee Representation
The Decision reinforces employees' right to organise and collectively represent their interests through recognised labour unions, providing a clearer legal framework for workplace representation.
Promoting Good Governance
Labour unions are now subject to enhanced governance requirements designed to improve accountability, transparency, and effective internal administration.
Enhancing Legal Protection
The regulations introduce additional safeguards for elected union representatives, ensuring they can carry out their functions without undue interference.
Clarifying Employer Obligations
Employers are provided with clearer guidance regarding their legal responsibilities when interacting with recognised labour unions and their representatives.
Key Changes Introduced by Ministerial Decision No. 284/2026
1. New Framework for Establishing Labour Unions
The Decision sets out detailed procedures governing the establishment and registration of labour unions.
Key aspects include:
- Formation Procedures – The regulations establish a structured process for creating labour unions, ensuring that all legal requirements are met before recognition is granted.
- Registration Requirements – Specific documentation and approval procedures have been introduced to standardise the registration process and improve regulatory oversight.
- Election of Administrative Boards – Clear rules now govern the election of union leadership, helping to ensure democratic representation and transparency.
- Dissolution Procedures – The Decision also specifies the circumstances and procedures under which a labour union may be dissolved in accordance with the law.
These provisions create greater certainty for employees wishing to establish labour unions while providing a consistent regulatory framework for employers.
2. Stronger Governance Requirements
One of the most significant reforms is the introduction of enhanced governance standards for labour unions.
The regulations require unions to maintain sound administrative practices through:
- Transparent Management – Union activities and decision-making processes should be conducted openly and in accordance with the regulations.
- Democratic Elections – Administrative board members must be elected through prescribed procedures that promote fair representation.
- Proper Record Keeping – Labour unions are expected to maintain accurate records of meetings, resolutions, financial matters, and administrative activities.
- Financial Accountability – Enhanced financial governance measures promote responsible management of union resources and improve institutional integrity.
These governance requirements aim to strengthen confidence in labour unions while promoting responsible administration.
3. Enhanced Protection for Union Representatives
The Decision provides additional legal safeguards for elected union representatives.
Among the notable protections are:
- Protection Against Unfair Employment Actions – The regulations introduce mechanisms to help prevent adverse employment actions taken solely because of an employee's union role.
- Review Committee – A specialised committee has been established to examine alleged violations involving union representatives and review employment decisions affecting them.
- Restrictions on Workplace Transfers – Employers may not transfer elected union representatives away from the workplace serving as the union headquarters without their consent, helping preserve effective employee representation.
These protections are intended to promote constructive dialogue between employers and employee representatives.
4. Employer Compliance Obligations
Although the Decision primarily regulates labour unions, it also introduces practical obligations for employers.
Businesses should ensure they:
- Recognise Lawfully Established Labour Unions – Employers should engage appropriately with recognised labour unions operating within their organisation.
- Cooperate with Union Representatives – Legitimate communications and consultations with authorised representatives should be facilitated in accordance with the regulations.
- Avoid Interference – Employers should refrain from actions that may improperly restrict or interfere with lawful union activities.
- Review HR Practices – Internal disciplinary procedures, transfers, and workplace policies should be reviewed to ensure compliance with the new legal framework.
Failure to comply may increase the risk of employment disputes and regulatory scrutiny.
5. Transitional Arrangements
To ensure continuity, the Decision contains transitional provisions for existing labour unions.
These include:
- Continuation of Existing Administrative Boards – Administrative boards elected under the previous regulations may continue to serve for the remainder of their approved terms.
- Future Compliance – New elections, registrations, governance procedures, and administrative activities must comply with Ministerial Decision No. 284/2026.
This approach allows organisations sufficient time to transition to the updated regulatory framework without disrupting existing operations.
Practical Steps for Employers
Organisations should take proactive measures to prepare for the new regulatory requirements, including:
- Reviewing employment policies and employee handbooks.
- Updating HR procedures relating to employee representation.
- Training HR personnel and management on the new regulations.
- Reviewing disciplinary and transfer procedures involving union representatives.
- Seeking legal advice where existing workplace practices may require amendment.
Early compliance will help minimise legal risks and support effective employee relations.
Conclusion
Ministerial Decision No. 284/2026 represents an important milestone in the development of Oman's employment law framework. By strengthening governance, enhancing employee representation, and clarifying employer responsibilities, the regulations aim to promote a more transparent and balanced workplace environment.
Employers should view these changes as an opportunity to review internal employment practices and ensure that their organisations remain fully compliant with the evolving legal landscape.
How YLAW Can Assist
Younis Al Amri & Sayed Taher Advocates & Solicitors advises domestic and international businesses on all aspects of Omani employment and labour law, including:
- Employment law compliance
- HR policy reviews
- Employment contracts
- Employment dispute resolution
- Regulatory compliance audits
Our team works closely with employers to develop practical, commercially focused solutions that minimise legal risk while supporting effective workforce management.